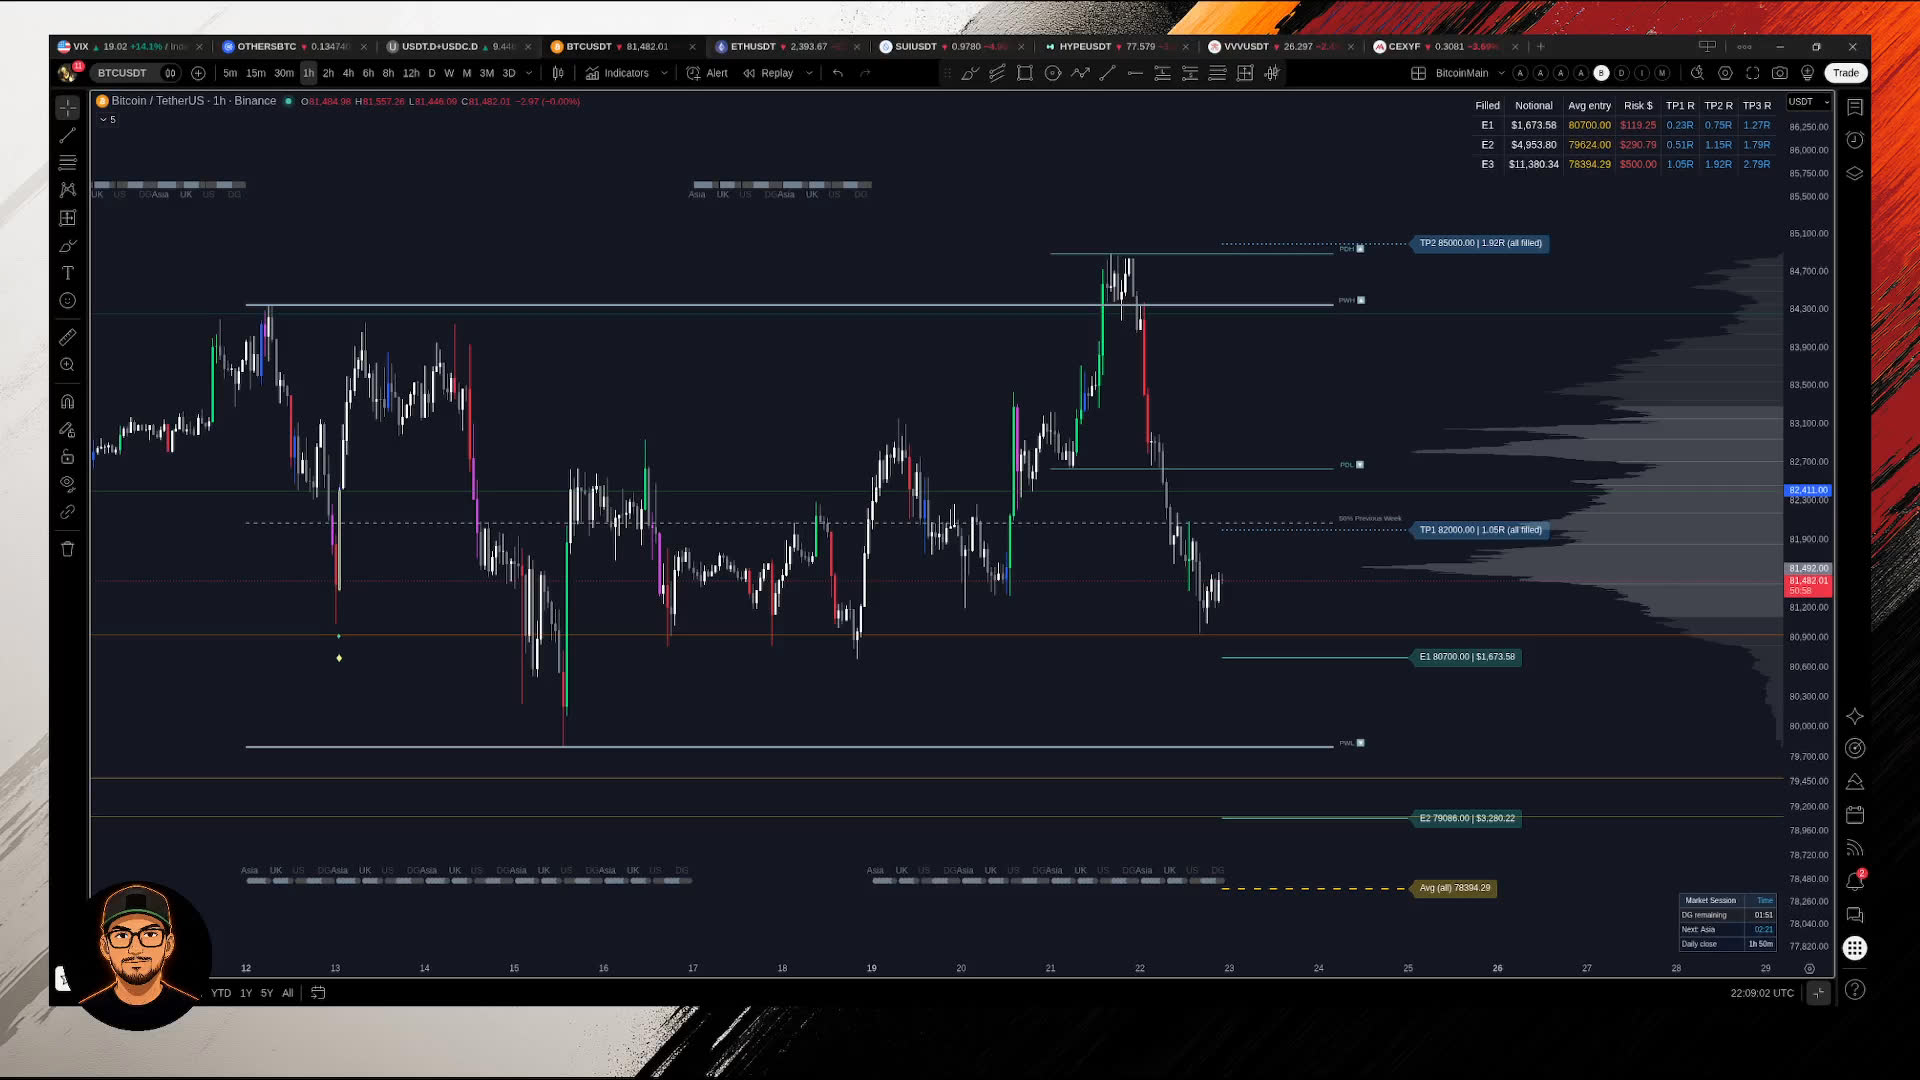
HACK Daily close above the expansion gate invalidates the bearish thesis under my system. Breaking back below would be a huge red flag and I would sell everything.
Trusted investing communities
Inside the mind of the top investors
Experience Slice App, a social platform where you can learn from and engage with top investors.
50,000+members50+active verified mentors100+daily analyses


Life and Value After Default: A Follow-Up
In March 2012, amid the depths of the eurozone crisis and with Greece’s private-sector involvement (PSI) underway, we wrote a note titled “Equities – There’s Life and Value After Default” on our former Blogspot Blog “Macronomics”.
The argument was that the Athens Stock Exchange (ASE) and Icelandic equities could recover strongly once the acute phase passed. It drew on historical post-default recoveries (Russia 1998, Argentina 2001) and contrasted Iceland’s cleaner “let the banks fail” approach with more drawn-out European bank resolutions.
Fourteen and a half years later, the results (price indices, approximate levels from March 2012 to late October 2026) are as follows:
- ASE (ATHEX Composite): ~729 → ~2,588. Total return +255%, CAGR ~9.1%.
- OMX Iceland All-Share: ~644 → ~1,981. Total return +208%, CAGR ~8.0%.
- Euro Stoxx 50: ~2,530 → ~6,046. Total return +139%, CAGR ~6.2%.
- S&P 500: 1,408 → ~7,650. Total return +443%, CAGR ~12.3%.
Both markets more than t


This Is a Rate Selloff, Not a Reason to Leave. why this is not the time to walk away.
I know this stretch feels heavy. The AI names have been sold for two weeks, the headlines are all about debt and spending, and every bounce gets sold. But step back and look at what kind of selloff this actually is. The demand side of this market keeps proving itself earnings are beating, guidance is being raised, order books are growing. What broke was not the fundamentals. What broke was the cost of money, when the 10-year yield spiked in early October and made every borrowed dollar more expensive.
That part is now reversing. The 10-year topped near 5.36%, failed to go higher, and has rolled over to 4.95%, breaking below its 50-day average for the first time in the entire climb. Yields peaking and easing into a midterm is exactly what happened in 2018 — and what followed was one of the strongest post-midterm runs on record, as the uncertainty cleared and the seasonal bid returned into year end.
So the
Government debt vs primary balance, 2026 (% of GDP):
Approximate 2026 positions (IMF Oct 2026):
- Greece: debt ~136%, primary ~+3.4%
- Portugal: debt ~90%, primary ~+1.7%
- Ireland: debt ~40%, primary ~+0.8%
- Italy: debt ~138%, primary ~+0.9%
- Spain: debt ~98%, primary ~–0.2%
- France: debt 118.5%, primary –2.9%
- UK: debt ~102%, primary ~–1.2%
- US: debt ~127%, primary ~–3.5%
- Japan: debt ~200%, primary ~–1.5%
France remains an outlier on the primary-balance side relative to its debt level, while the US sits even lower on the primary balance. Exact primary-balance figures for every country are not uniformly published in the public DataMapper extracts; values are consistent with the October 2026 vintage and overall fiscal balances reported by the IMF.

France troubles growing with concerning PMI for services:
GDP growth finally came in at zero in Q2 and –0.2% in Q1, both revised down by INSEE. The government’s +0.7% full-year target is now out of reach.
September’s services PMI rebound to 51.2 proved fleeting. October’s flash dropped back to 48.4 (composite and services), manufacturing at 49.3. Manufacturing new orders collapsed to 44.9, employment fell for a sixth straight month, and business confidence hit a six-and-a-half-year low (2027 election and fiscal worries). Political and financial conditions tightened further.July’s services PMI (49.6) already pointed to barely positive Q3 growth. Banque de France and INSEE still see +0.1% q/q for Q3. But without a rebound, the Q4 average would settle in the 47–48 zone.Without a rebound in new orders and employment, services cannot take over.
With services PMI stuck in the 47–48 range, Q4 should come in between –0.2% and –0.4% q/q.
That would push full-year 2026 into a mild recession (around

This Railway hack got real (for me). Woke up this morning to find an API key I hadn't rotated was taken in the attack. They ran up $100 over night asking OpenAI thousands of questions non-stop.
This is what I talked about in 'Enact the Noah Protocol' after the Hugging Face breach.
When you looked into the post-mortem details you realised the new AI models are highly persistent and potentially unstoppable. They can hack anything given enough time.
It looks like the API key was used to ask lots of image generation requests. This may have been part of a hack to train an AI model.
It has made me wonder if blockchain architecture is a solution to unstoppable AI cyber attacks. Rather than have one centralised data access point, which is hackable, make the AI have to hack the entire blockchain at once, which is much harder, and more expensive.



S&P 500: Cap-Weighted vs Equal-Weight
Cap-weighted SPY was dragged down by Semis/Tech.
Equal-weight RSP could not care less and advanced on a bad NDX and SPX day.
And, yes, S&P 500 breadth has been improving lately.


ES Elliott Wave Analysis
- ES miraculously failed to make a new low by 0.75, as non-tech stock held better; TBD whether this will survive by the next morning
- (A)-(B) sub-micro count, with (B) being an extreme expanded flat as posted earlier by beingkind, fits both the gray and the blue count

Market-
this is a tech-and-chips selloff, not a broad market one — the Nasdaq is down over 2% and the S&P about 1.3% while the Dow is essentially flat and small caps are holding up, with money rotating into defensives like staples and healthcare instead of heading for the exits. Semiconductors are the epicenter, with the SOX through that 11,000 floor and Lam's supply warning doing the damage, $META and $TSLA still dragging after their prints, and a $CRWV downgrade adding fresh pressure on the AI complex. The one offset is rates: the 10-year easing to 5.01% says this is repricing, not panic — jobless claims at a three-month low back that up. Into the close, the SOX close versus 11,000 is the tell, and $BE 's print tonight is the next test of whether quality AI-adjacent earnings can still get bought.
US 10 years Treasury notes yield vs France OAT 10 years yield - 6 months chart
US 10Y is acting as the relative safe-haven bid amid France’s self-inflicted fiscal and political crisis—exactly what the dual-axis chart is illustrating.
Over the six-month window, both US10Y (orange) and FR10Y (blue) have been in a clear uptrend, driven by the common global factors of sticky inflation, elevated energy prices (Brent above $110 on Middle East/Gulf disruption), and “higher for longer” policy pricing. The acceleration from September is visible on both lines. The important story is the relative performance, especially the latest stretch: French yields have broken above US yields (FR ~5.076–5.11%, US ~5.00%) for the first time since 2013, while US yields have simultaneously eased on the day on safe-haven demand.
What’s driving the French side (the “woes”) France is the clear idiosyncratic underperformer in the G7/euro-area complex:
- 10-year OATs have hit levels last seen in 2002 and the OAT–Bund spre

Discover
Find the mentor that matches your market style.


Rajeev Desai
@Rajeev Desai
In Indian stock market for over 30 Yrs. Not SEBI registered or not registered anywhere in the world. AS PER SEBI GUIDELINES-- I CAN'T GIVE BUY/SELL/HOLD CALLS. I CAN'T GIVE TARGETS. I want to write that , this is a mentorship platform. If you want to buy stock I discuss, do it at YOUR OWN RISK. For any queries to this site, Silce, write here, contact@slice-app.io
Stock
Crypto
+1
Posts1,491
Comments9,940

JustDario
@JustDario
Hong Kong-based entrepreneur, angel investor, and finance veteran with over a decade of experience in trading, securities structuring, derivatives, and fintech in Europe and Asia. My focus is on data-driven analysis of macro and stocks to identify investment opportunities, especially asymmetric ones. My public research is available on justdario.com.
Stock
Macro
+1
Posts306
Comments171