
Sometimes you get lucky.
We bought HKEX in October ‘24 as a levered way to play a boom in Chinese and HK equities off depressed levels (HKEX Our China FOMO Play).
So far the China bull market has been underwhelming.
We’re still waiting.
But things might work out for us in HKEX in a new unexpected way.
There is suddenly a lot of government momentum to build an ecosystem of offshore CNH investment products.
And HKEX is at the center of it.
The underwhelming growth of of CNH
Twenty years ago, during the exciting 8% GDP growth years of the early 2000’s, it was predicted China would become the largest economy in the world. Naturally, as China overtook the US in economic size, Chinese RMB would overtake the dollar as the most important currency in the world.
The fly in the ointment to this view was that RMB internationalisation required an open currency market, and for some reason Chinese officials have continually opposed that. So RMB internationalisation stalled. You can’t be the reserve currency with exchange controls.
Then China came up with an idea. A work around.
In 2010 China launched CNH; an offshore version of Chinese RMB (CNY). Onshore CNY would be used for mainland Chinese payments, but CNH (with ‘H’ standing for Hong Kong) would be the offshore version; freely tradable around the world. Hong Kong would be the main hub, with the largest deposits of CNH, but there would be trading hubs in London, Frankfurt and Singapore too.
That was the vision.
I was working at HSBC when CNH was announced. For the bank it was an exciting new product, which perfectly fit their market position as the biggest bank in HK. HSBC was intent on making the most of the opportunity. Lots of shiny, thick CNH primers, filled with interest charts, were printed out. Expert analyst visits were booked with all the big clients to explain the world changing ramifications CNH would have and how HSBC would help you with all your CNH needs. Freely tradable CNH was the missing piece which would now turbo charge RMB internationalisation.
Except CNH never became a big thing either.
I mean it grew OK, there was a build up of CNH deposits in Hong Kong, but it didn’t make people want to hold RMB other than when they needed to trade with a Chinese counterparty.
Freely CNH was an improvement, but there was still an obvious missing ingredient.
The CNH Ecosystem
Once I have these CNH what am I supposed to do with them?
Store them in a HK bank account?
Zzzzzzz……
This missing piece was that CNH needed an investment ecosystem.
Like the dollar.
Someone pays you in USD? Great. There are millions of things to do with those $’s. You can buy stocks in the greatest stock market in the world. And you can buy/write options on those stocks, You can buy commodities. You can buy bonds (lots of bonds). Then you can hedge them, repo them, swap them, whatever.
This investment ecosystem was the missing piece and for some reason the Chinese government never really prioritised it. I think because there was some uncertainty about Hong Kong’s role in the Chinese financial ecosystem. There had always been a push to build up the financial markets in Shanghai (equities and commodities) and de-emphasise Hong Kong. So Hong Kong kind of whithered. Neglected.
Then in 2025 something flipped.
Look at the pace of developments (remember HKEX owns LME):
March 2025: HKEX Signs MOU with CMU OmniClear to Enhance the Post-Trade Securities Infrastructure of Hong Kong’s Capital Markets
March 2025: OTC CLEAR TO ACCEPT CHINA GOVERNMENT BONDS, POLICY BANK BONDS AS COLLATERAL FOR ALL DERIVATIVES FROM 21 MARCH 2025
April 2025: The London Metal Exchange (LME) announces its approval of the first four LME-licensed warehouse facilities in Hong Kong.
June 2025: HKEX WELCOMES LAUNCH OF 30-YEAR SWAPS TRADING IN NORTHBOUND SWAP CONNECT
November 2025: HKEX MAKES STRATEGIC INVESTMENT IN CMU OMNICLEAR HOLDINGS TO ACCELERATE DEVELOPMENT OF HONG KONG’S FIC ECOSYSTEM
December 2025: HKEX EXPANDS INDEX BUSINESS WITH LAUNCH OF HKEX TECH 100 INDEX
April 2026: HKEX BUILDS FIC LEADERSHIP TEAM WITH NEW APPOINTMENT
May 2026: HKEX BUILDS COMMODITIES TEAM WITH NEW APPOINTMENT
June 2026: HKEX TO DEBUT CHINA GOVERNMENT BOND FUTURES ON 3 AUGUST 2026
June 2026: LME Clear enhances CNH cash and warrants as collateral
July 2026: HKEX, CIPS SIGN MOU TO STRENGTHEN HONG KONG’S OFFSHORE RMB SETTLEMENT INFRASTRUCTURE
August 2026: HKEX WELCOMES MAINLAND INSURANCE FUNDS TO INVEST IN HONG KONG ETFS
September 2026: The London Metal Exchange (LME) confirms that trading in its new LME Steel HRC Shanghai futures contract will commence on 27 October 2026
September 2026 HK CEO Address: HKEX announces new RMB‑denominated and physically settled gold futures contracts to boost global influence of the RMB in the pricing of precious metals.
November 2026: HKEX LAUNCHES OFFSHORE RMB BOND INDEX
I don’t know why the switch flipped. But it has.
China is now going full steam ahead to build out HK as the offshore RMB financial center with bonds, bond futures, bond indices, collateral management, clearing, gold trading, commodity contracts, and ETF’s.
HKEX is building out that rich ecosystem of things to do with your CNH. HKEX are also trying to make CMU Omniclear the HK version of Euroclear or London Clearing House. It all comes together.
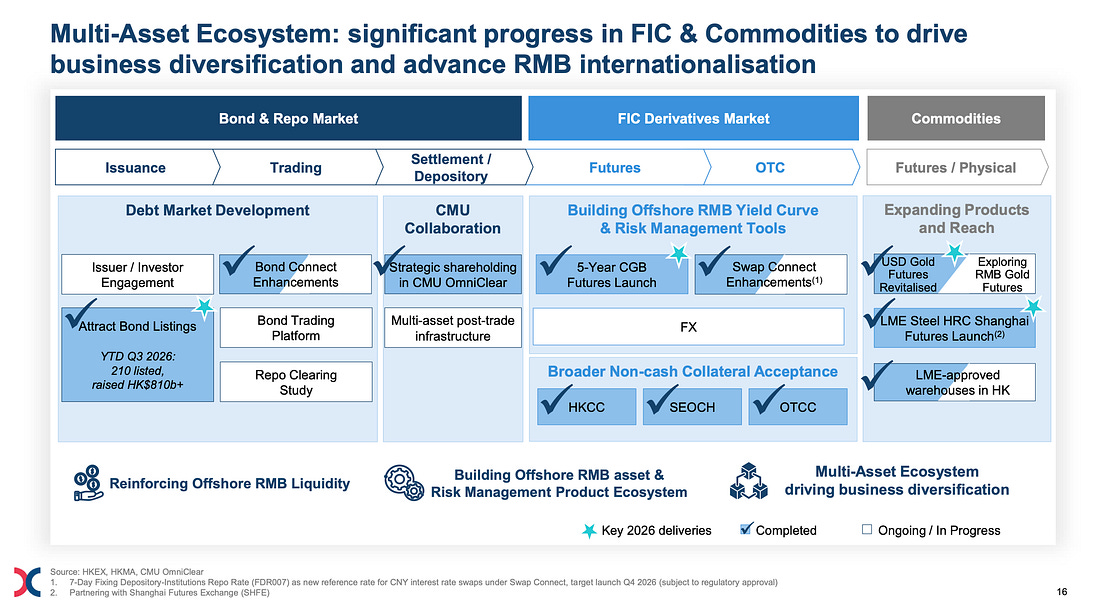 HKEX Q3 Results Presentation
And you see the volume of HK listed bonds building.
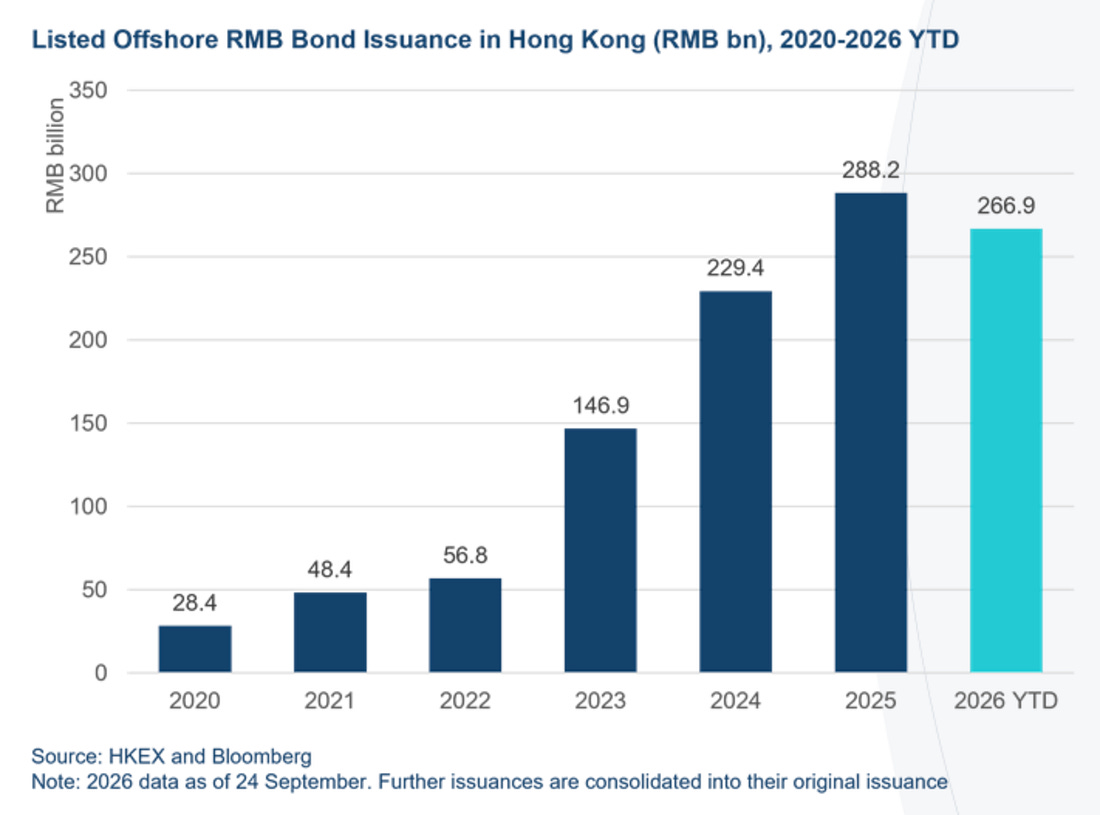
It helps that Chinese interest rates are less than 2% while US rates are closer to 5%.
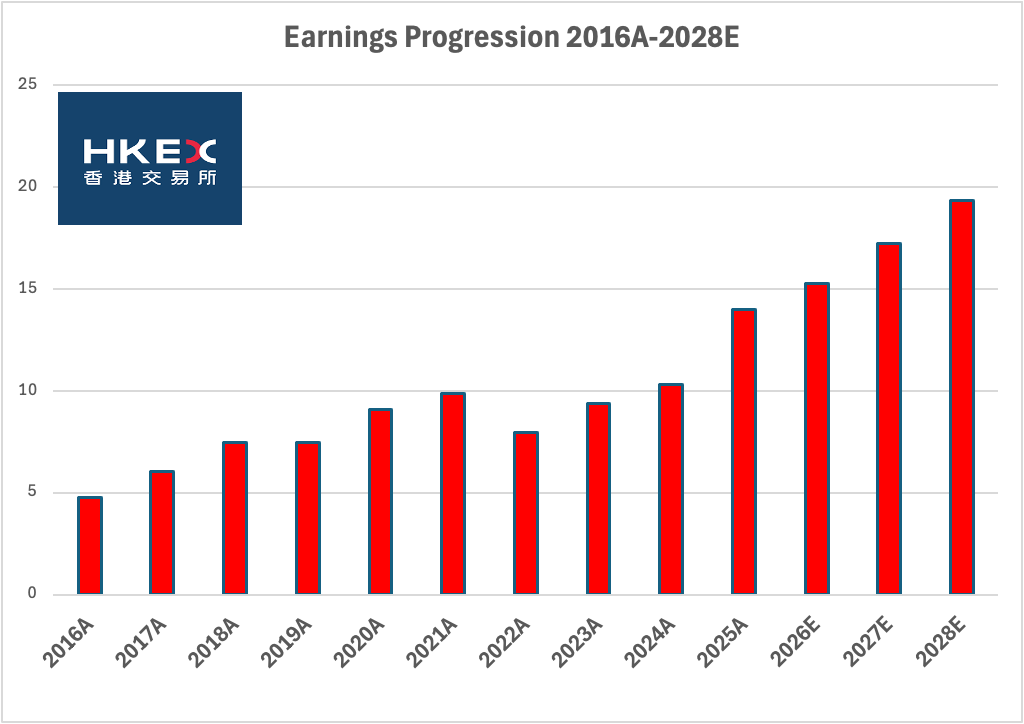
HKEX EPS Progression
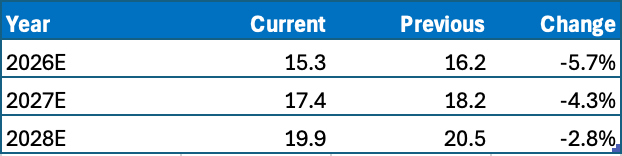
It’s really hard to forecast exchange earnings, but here are my forecasts.
I have modelled a 12% EPS CAGR from 2025-2028.
EPS grows from HK $15/share in 2026 to HK$20 in 2029
While derivatives volumes have been strong (especially LME), cash equities have flatlined recently.
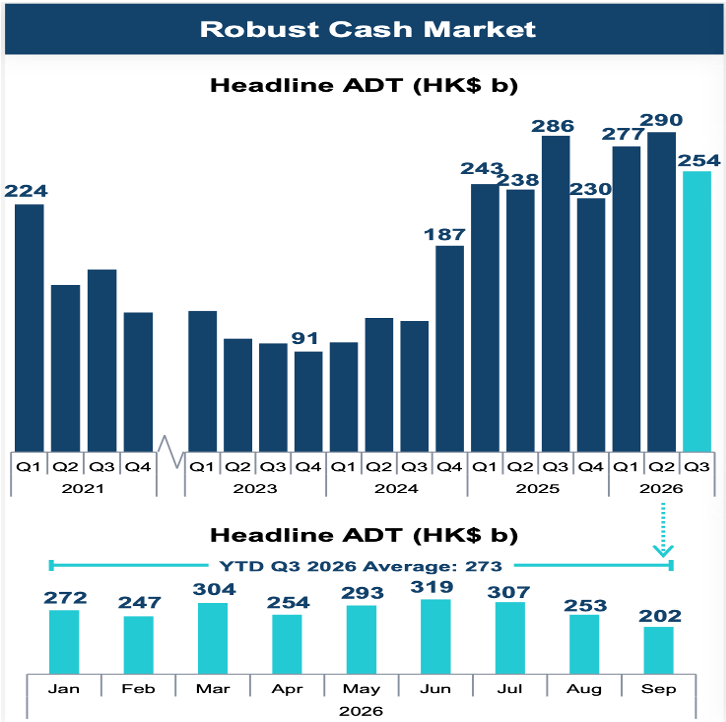
Because of the recent slowdown in cash equity volumes, which can also turn on a dime, I have nudged my estimates 5% lower.
Valuationwise, HKEX is attractive relative to its history, although not super cheap. But it rarely is. It always trades at a premium. Partly, because it pays out 90% of earnings in dividends. The forward estimated dividend yield is 3.6%.
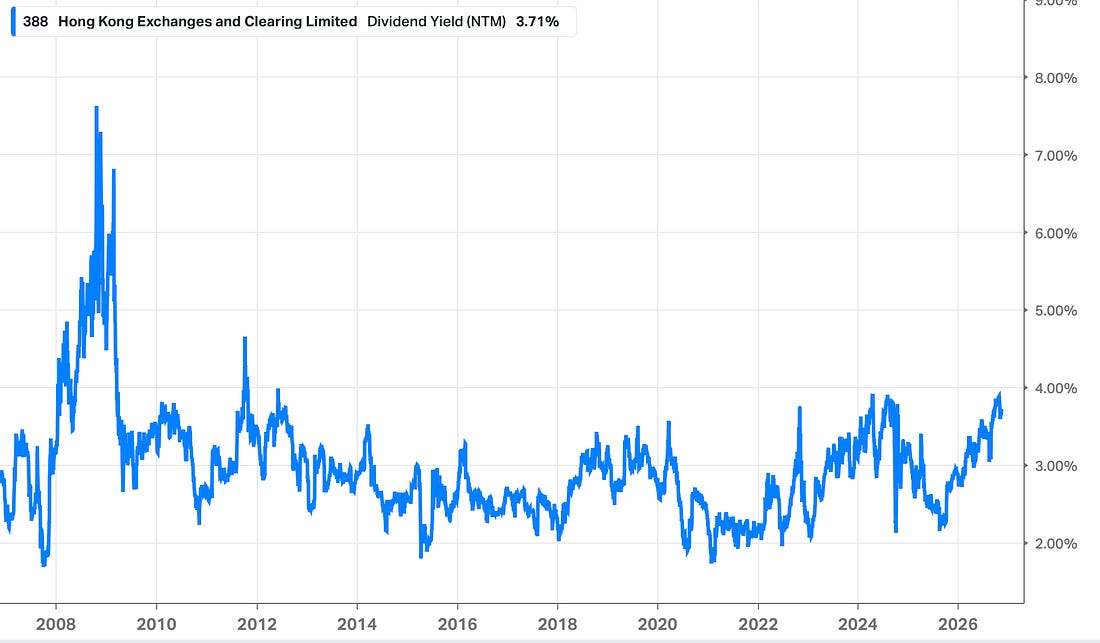
Traditionally, the real moves in HKEX have come not from under valuation but from big moves in the Equities market. Going forward we could have a second driver, the emergence of a mini CME.
Below is a link to our HKEX model.
HKEX Earnings Model (November 2026)
Regards,
Erik